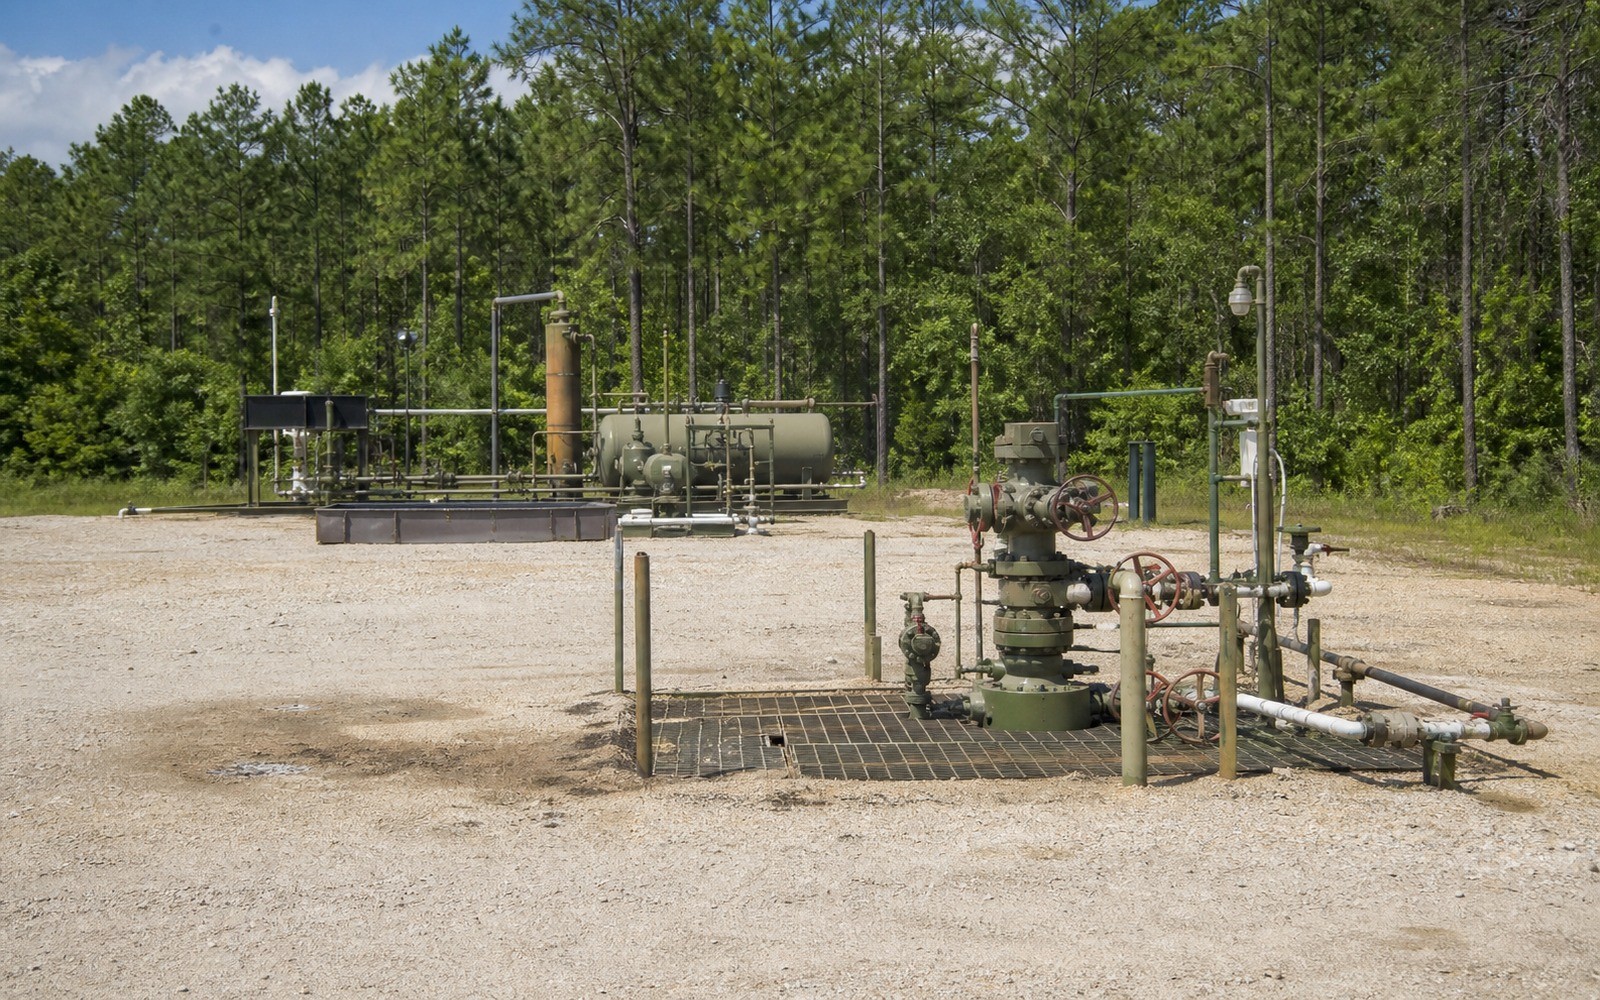
Tuscaloosa Marine Shale Mineral Rights
Few plays in recent American oil history saw such a wide gap between early enthusiasm and eventual results as this one, and mineral owners here deserve a straight account of what happened.
The Tuscaloosa Marine Shale runs across a band of southwest Mississippi and southeast Louisiana, and it drew genuine industry excitement in the early 2010s as operators hoped it might replicate the success other oil shale plays were having elsewhere in the country. High clay content in the rock made horizontal drilling and completion technically difficult and expensive compared to plays with more favorable rock properties, and well results across the play were inconsistent enough that most major operators pulled back within a few years of the initial push.
What made the geology so difficult here
The Tuscaloosa Marine Shale's high clay content behaves differently under hydraulic fracturing than the more brittle, silica-rich shale that made plays like the Eagle Ford and Bakken successful. Clay-rich rock tends to absorb fracturing fluid and close fractures back up more readily, which made it harder to achieve the kind of sustained, predictable production operators were seeing elsewhere. Well costs also ran high relative to typical production rates, a combination that made the play's economics marginal even during periods of strong oil prices.
The operators who tried and largely left
Goodrich Petroleum and Encana were among the companies that invested significant capital testing the play through the early-to-mid 2010s, and both scaled back or exited their Tuscaloosa Marine Shale positions within a few years as results failed to justify continued investment at the pace originally planned. This wasn't a case of the industry giving up too early on a play that just needed more time; it reflected genuine, repeated technical and economic disappointment across multiple operators and well designs.
What's left today
Some smaller, more focused operators have continued limited activity in the play's better-performing pockets, applying completion technique refinements that weren't available during the original rush. This has kept a small amount of ongoing interest alive rather than the play going completely dormant, but it's nowhere close to the broad, multi-operator development that was originally anticipated. If your family's minerals sit here, it's realistic to expect continued limited, selective activity rather than a renewed boom.
An honest approach to selling here
Given this history, any offer on Tuscaloosa Marine Shale minerals should be evaluated with real skepticism toward optimistic pricing and real appreciation for the fact that some legitimate, if limited, buyer interest does still exist. Owners who remember the early-2010s enthusiasm should recalibrate expectations to the play's actual track record rather than that original promise. A buyer or broker who's straightforward about this history, rather than one still pitching the play's old talking points, is the one worth working with.
Legacy leases signed during the original enthusiasm
Many landowners across the Louisiana and Mississippi counties in this play signed leases during the original 2010 to 2013 rush, often with bonus and royalty terms negotiated under the assumption that sustained development was coming. Those leases have since expired, been extended, or in some cases lapsed entirely as operators failed to drill within their primary term, and it's worth checking your own lease status carefully rather than assuming an old agreement still governs your minerals. If your lease has expired without a well being drilled, you may be in a position to negotiate fresh terms with whichever operator, if any, expresses renewed interest, rather than being bound to terms set during a very different market environment. Parish and county clerk records will show whether your original lease was ever formally released, which is worth confirming rather than assuming based on memory alone, and that confirmation should come before, not after, you sign anything new covering the same tract, since an unreleased old lease can complicate a fresh agreement more than most owners expect. It's a small step that protects you from a much larger headache down the road. Take the extra day to confirm it rather than assuming your memory of the paperwork is accurate.
Questions Owners Ask Before Authorizing a Sale Process
These answers keep every bidder working from the same asset definition, evidence, timing, access, and requested terms.
Why did the Tuscaloosa Marine Shale fail to develop like other oil shale plays?
High clay content in the rock made hydraulic fracturing less effective and completions more expensive relative to typical well production, producing inconsistent results that discouraged sustained investment.
Are any operators still active in the Tuscaloosa Marine Shale?
Yes, on a limited scale, with smaller operators working the play's better-performing pockets using refined completion techniques, though nowhere near the pace originally anticipated.
Is there any chance this play sees renewed major investment?
It's possible if technology or economics shift favorably, but the play's repeated disappointing results across multiple major operators make this a reasonable but not likely near-term expectation.
How should I value an offer on my Tuscaloosa Marine Shale minerals?
Weigh it against the play's actual limited activity level rather than its early-2010s reputation, and favor a buyer who's transparent about that history over one pricing against outdated expectations.
Carry the same property schedule, evidence room, bidder rules, deadline, clarification record, and conveyance scope into these related guides.
Want to organize a comparable, documented mineral-sale process?
Send the county and state, owner name, deed reference, operator or payor, recent statement, lease, division order, probate or trust record, and any written offer already received.